
Habits That Quietly Undermine a Household Budget
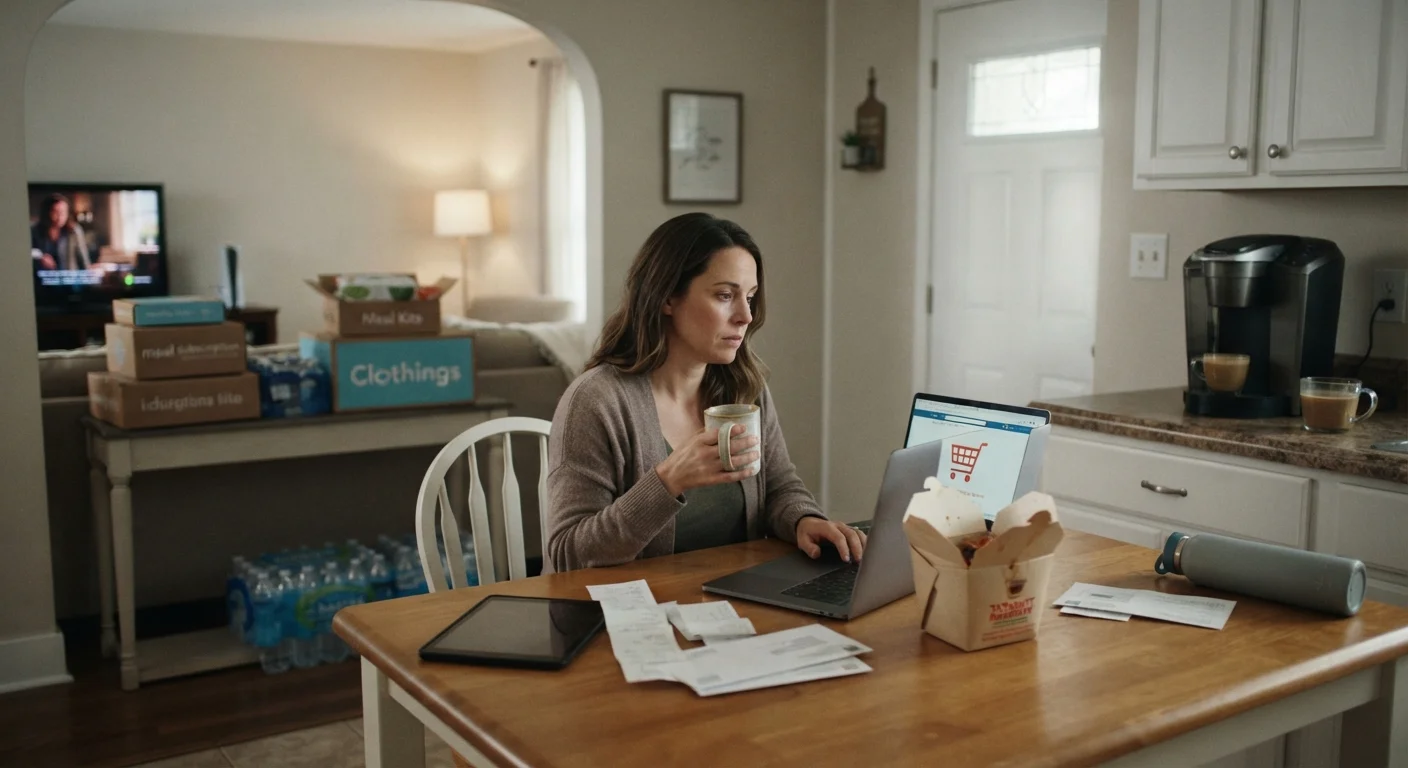
Photo: SmartGlobetrotter.net editorial
Key Takeaways
- Subscriptions and recurring fees often go unreviewed for months or years, costing more than expected.
- Convenience spending, like frequent takeout or last-minute purchases, adds up faster than most budgets account for.
- Irregular expenses such as annual fees or car maintenance are predictable but often left out of monthly plans.
- Minimum credit card payments extend repayment timelines and increase total interest paid.
- Vague budget categories hide overspending by making it hard to see where money actually goes.
- A regular spending review, even monthly, can catch budget drift before it becomes a pattern.
Why small habits do the most damage
Most household budgets don't collapse from one large mistake. They erode through patterns that feel minor in the moment: a subscription here, a convenience purchase there, a bill left on autopay long after its usefulness expired. Because no single instance looks alarming, these habits stay in place for months or years.
The list below covers habits that show up frequently across American households and are easy to miss precisely because they blend into routine. For a broader framework on structuring your monthly plan, see our guide to building a budget that holds up month to month.
This article is for general informational purposes only and does not constitute personalized financial advice. For guidance suited to your specific situation, consult a licensed financial professional.
Keeping subscriptions on autopay without reviewing them
Streaming services, fitness apps, cloud storage plans, and software trials all charge automatically. Each one may cost only a few dollars per month, but a household carrying eight to twelve active subscriptions can spend well over $150 monthly on services that see irregular or no use. Autopay removes the friction that might otherwise prompt a cancellation decision.
A simple fix: pull up your bank or credit card statement and mark every recurring charge. For each one, confirm it is still in active use and that the current tier matches actual usage. Services you have not used in 30 days are worth canceling or downgrading.
Autopay removes the friction that might otherwise prompt a cancellation decision.
Treating convenience spending as a fixed cost
Takeout, delivery fees, single-cup coffee purchases, and last-minute online orders are variable expenses, but many households spend nearly the same amount on them every month without ever putting a number to it. Because these purchases feel discretionary, they rarely appear as a named line item in a written budget.
Naming the category and assigning a monthly ceiling to it changes the dynamic. Once there is a visible limit, individual purchases get weighed against it rather than treated as isolated decisions. Home and lifestyle costs have a similar pattern; hidden household costs renters and homeowners overlook covers recurring home expenses that operate the same way.
Unnamed budget categories make it easy to overspend without ever noticing a pattern.
Leaving irregular expenses out of the monthly plan
Car registration, annual insurance premiums, back-to-school supplies, holiday gifts, and seasonal utility spikes are predictable. They happen every year at roughly the same time. Yet many households treat them as surprises because they do not appear every month.
The standard approach is to estimate each irregular expense for the year, divide by 12, and set that amount aside monthly into a separate account or envelope. When the bill arrives, the money is already there rather than coming out of that month's general budget.
Predictable annual costs still catch households off guard when they are left out of the monthly plan.
Making only minimum payments on revolving credit
Minimum payments on credit cards are calculated to keep an account current, not to pay it down efficiently. On a $3,000 balance at 22% APR, paying only the minimum can extend the repayment period to a decade or more and add hundreds of dollars in interest over that time. The minimum payment keeps the account in good standing, but it does not reduce the balance at a rate that matches most people's intentions.
Paying more than the minimum, even modestly, reduces both the timeline and the total interest cost. This is general information; your actual interest and repayment timeline depend on your specific balance, rate, and payment amounts.
Minimum payments keep an account current but do not reduce the balance at a meaningful rate.
Using vague budget categories that hide real spending
Categories like 'miscellaneous' or 'personal' absorb purchases that don't fit elsewhere, which makes them nearly impossible to analyze. When a category has no specific meaning, there is no way to know whether spending in it is normal, rising, or inflated by a temporary pattern.
Replacing vague categories with specific ones, such as separating 'dining out' from 'groceries' or 'clothing' from 'household supplies,' gives each type of spending its own record. Patterns become visible over two or three months. Seniors managing a fixed income face an especially direct version of this problem; managing money on a fixed income covers approaches for keeping essential expenses clearly defined and in view.
Vague categories make it impossible to know whether spending in them is normal or rising.
Skipping the review after a life change
A job change, a move, a new household member, or a paid-off loan each shifts the budget's baseline. Households that do not update their plan after a change often continue spending against old assumptions, either missing an opportunity to redirect freed-up money or failing to account for new costs that have appeared.
A budget review after any significant change, even a short one, re-aligns the plan with current reality. If you want a structured starting point for that process, our monthly budgeting walkthrough covers how to adjust when circumstances shift.
A budget built for last year's circumstances will not accurately reflect this year's spending.
Catching budget drift early
Most of the habits above share one feature: they become visible only when you look for them. A monthly review of bank and credit card statements, even a brief one, surfaces charges that have outlived their purpose and categories where spending has quietly expanded.
Annual reviews matter too, since some costs, like insurance premiums, HOA fee changes, or subscription price increases, reset on a yearly cycle. Our year-end financial checklist for households on a budget walks through what to examine before a new year starts. If travel is part of your spending, overlooked expenses that inflate the real cost of a vacation covers the costs most people underestimate when planning a trip.
Fixed-income households face extra pressure
The content provided on our blog site traverses numerous categories, offering readers valuable and practical information. Readers can use the editorial team’s research and data to gain more insights into their topics of interest. However, they are requested not to treat the articles as conclusive. The website team cannot be held responsible for differences in data or inaccuracies found across other platforms. Please also note that the site might also miss out on various schemes and offers available that the readers may find more beneficial than the ones we cover.