
Why Your Credit Score Dropped (And What You Can Do About It)
Photo: SmartGlobetrotter.net editorial
Key Takeaways
- A single missed payment can lower your credit score significantly and stays on your report for seven years.
- High credit utilization is one of the fastest ways to drag down your score, even without missing payments.
- Hard inquiries from new credit applications cause a small, temporary dip in your score.
- Closing old accounts can shorten your credit history and reduce available credit, both of which lower your score.
- Errors on your credit report are more common than many people realize and can be disputed at no cost.
How credit scores work and why they change
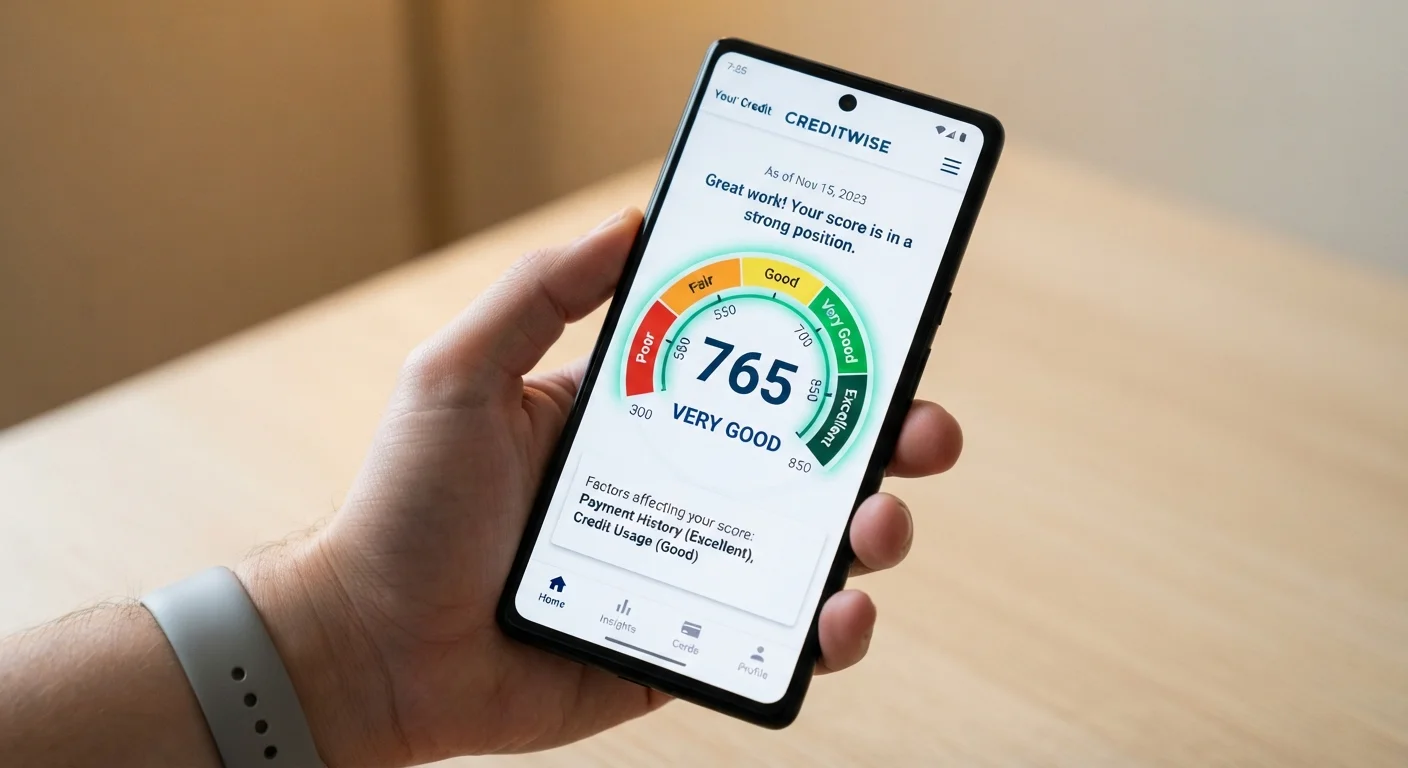
Your credit score is a three-digit number, typically ranging from 300 to 850, that lenders use to judge how likely you are to repay debt. The most widely used scoring models weight five categories: payment history, credit utilization, length of credit history, credit mix, and new credit inquiries. Payment history and utilization together account for roughly two-thirds of most scores, which is why problems in those two areas tend to cause the sharpest drops.
Scores are recalculated whenever a lender or bureau receives updated information. That means a single new late payment or a sharp rise in your card balance can change your score within weeks. The score does not reflect your income, savings, or overall financial picture, only how you have managed debt obligations reported to the bureaus.
Common mistakes that lower your score
Most credit score drops trace back to a small number of predictable behaviors. Understanding the mechanics behind each one makes it easier to respond quickly and avoid repeating the error.
Missing a payment, even by a few days, without realizing the impact.
Carrying a high balance relative to your credit limit, known as high credit utilization.
Applying for several new credit accounts in a short period.
Closing old credit card accounts to simplify finances.
Ignoring errors or outdated information on your credit report.
This article is for general informational purposes only and does not constitute financial or legal advice. Credit scoring models vary by lender and bureau. Consult a licensed financial professional for guidance specific to your situation.
Steps to start rebuilding your score
Recovery is possible for most score drops, though the timeline depends on the severity of the issue. A single late payment may take 12 to 24 months to stop weighing heavily on your score, while a collection account or bankruptcy can affect scores for several years.
The most reliable path forward is consistent, on-time payment across all open accounts. Even if you cannot pay a full balance, paying at least the minimum on time each month prevents additional late marks from stacking up. Reducing high balances is the next priority, since utilization changes are reflected quickly once a lower balance is reported.
Avoid credit repair companies that promise quick fixes
If errors appear on your report, the Fair Credit Reporting Act gives you the right to dispute them at no charge. Each bureau has an online dispute process, but submitting disputes in writing with documentation creates a clear record. Bureaus generally must investigate and respond within 30 days.
The content provided on our blog site traverses numerous categories, offering readers valuable and practical information. Readers can use the editorial team’s research and data to gain more insights into their topics of interest. However, they are requested not to treat the articles as conclusive. The website team cannot be held responsible for differences in data or inaccuracies found across other platforms. Please also note that the site might also miss out on various schemes and offers available that the readers may find more beneficial than the ones we cover.