
Health Insurance Decoded: A Plain-English Walkthrough for First-Timers
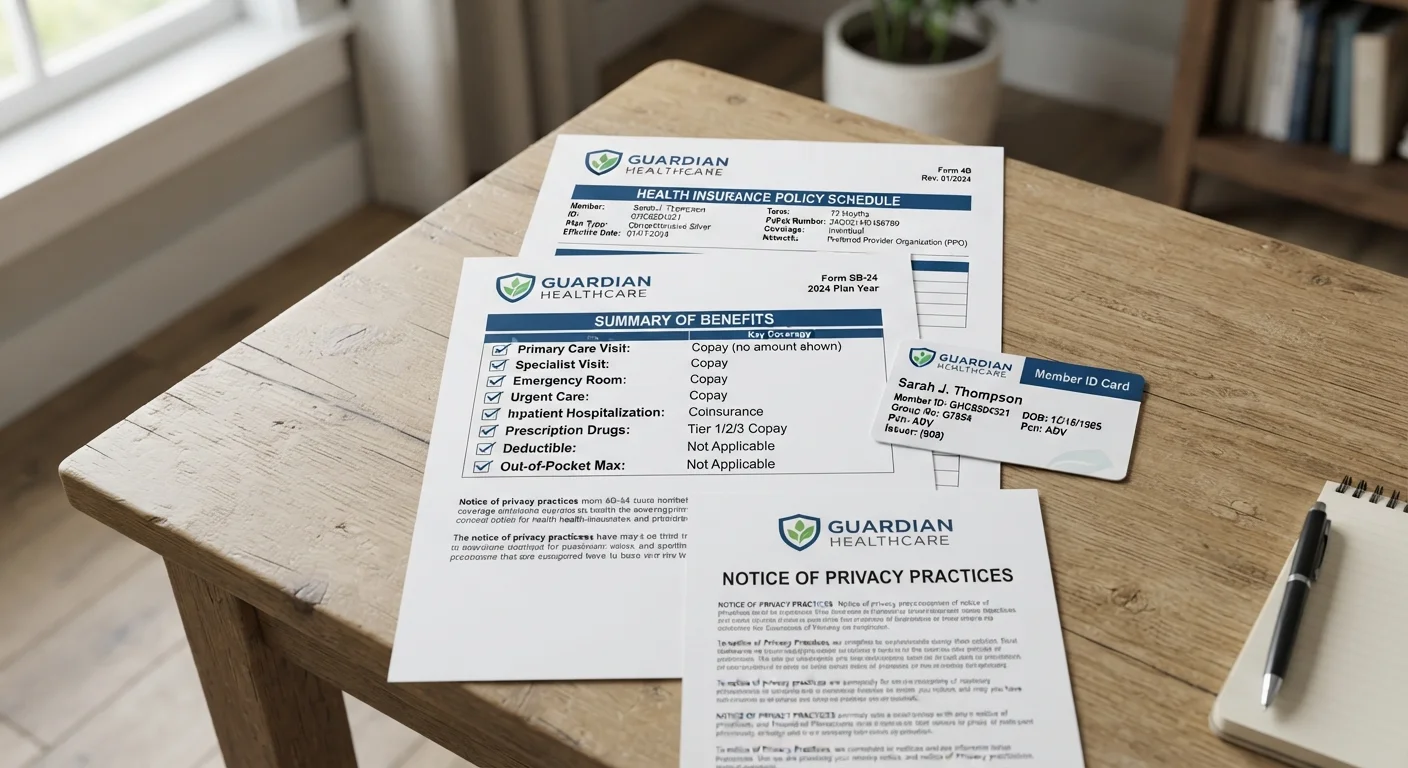
Photo: SmartGlobetrotter.net editorial
Key Takeaways
- Health insurance spreads the financial risk of medical care across a large group of people.
- You pay several different costs under a health plan, and no single number tells the full picture.
- Plan types such as HMO, PPO, and HDHP differ mainly in how you access care and what you pay out of pocket.
- Employer plans, Marketplace plans, Medicaid, and Medicare each serve different groups with different eligibility rules.
- Checking which doctors and drugs a plan covers matters as much as comparing the monthly premium.
How health insurance actually works
Health insurance is a financial arrangement. You pay a regular amount (a premium) to an insurance company, and in exchange, the company agrees to share the cost of covered medical care. The logic is straightforward: most people cannot predict when they will need expensive care, so spreading that risk across a large group makes individual costs more manageable.
When you receive a covered service, your insurer pays a portion of the bill based on the terms of your plan. How much the insurer pays and how much you pay depends on the specific cost-sharing structure built into your coverage. Those structures vary across plan types, which is why two plans with similar monthly costs can behave very differently when you actually use them.
Premium
The fixed monthly amount you pay to keep your health plan active, regardless of whether you use any medical services.
Deductible
The amount you pay for covered care each year before your insurance starts sharing the cost with you.
Copay
A flat fee you pay at the time of a specific service, such as a doctor visit or prescription pickup.
Coinsurance
Your share of a medical bill expressed as a percentage, paid after you have met your deductible.
Out-of-pocket maximum
The most you can be required to pay for covered services in one plan year. After hitting this limit, the plan covers 100% of covered costs.
In-network provider
A doctor, hospital, or other provider that has a contract with your insurance company, usually resulting in lower costs for you.
Formulary
The list of prescription drugs a health plan covers. Drugs on lower tiers of the formulary typically cost you less.
Open enrollment
A set window each year when you can sign up for, change, or drop a health plan without needing a qualifying life event.
This article is for general informational purposes only and is not medical, financial, or insurance advice. Consult a licensed professional for guidance specific to your situation.
The costs you pay: premiums, deductibles, and more
Most people focus on the monthly premium when comparing plans, but that number is only part of what you will spend. Four cost types work together, and understanding each one gives you a clearer picture of your total exposure.
- Your premium is due every month whether or not you use any care.
- Your deductible is what you pay for covered services before the insurance company starts sharing costs. A $2,000 deductible means you pay the first $2,000 of covered expenses each year.
- A copay is a flat amount due at the time of service. Many plans charge a fixed copay for primary care visits or prescription pickups.
- Your coinsurance is a percentage of the bill you owe after meeting your deductible. An 80/20 plan means the insurer pays 80% and you pay 20% of covered costs above the deductible.
These costs stop accumulating once you reach your plan's out-of-pocket maximum. After that point, the insurer covers 100% of covered services for the rest of the plan year. For a deeper look at how these figures interact, see how deductibles, copays, and coinsurance affect your wallet.
Types of health plans and what sets them apart
Plan type determines how you access care and what you pay when you go outside the insurer's network of providers.
HMO (Health Maintenance Organization)
HMO plans require you to choose a primary care physician who coordinates your care and provides referrals to specialists. Coverage is generally limited to in-network providers except in genuine emergencies. Premiums and out-of-pocket costs tend to be lower, but flexibility is more limited.
PPO (Preferred Provider Organization)
PPO plans let you see any provider without a referral, and they cover some out-of-network care at a higher cost to you. This flexibility usually comes with higher premiums and deductibles.
HDHP (High-Deductible Health Plan)
HDHPs have higher deductibles and lower premiums. They are often paired with a Health Savings Account (HSA), which lets you set aside pre-tax dollars for qualified medical expenses. These plans can work well for people who are generally healthy and want to build savings for future care costs.
Read the Summary of Benefits and Coverage first
Where people get coverage
Coverage comes from several distinct sources, each with its own eligibility rules.
Employer-sponsored plans
Most working-age Americans with insurance get it through an employer. The employer typically pays part of the premium, and the employee pays the rest through payroll deductions. Plan options are set by the employer, not the individual.
The Health Insurance Marketplace
People without access to employer coverage can shop for plans through the federal or state Marketplace. Income-based subsidies can reduce both premiums and out-of-pocket costs for qualifying households. Understanding how the Marketplace works and who it serves explains the subsidy structure in detail.
Medicaid
Medicaid covers low-income individuals and families. Eligibility thresholds vary by state, so what qualifies in one state may not in another.
Medicare
Medicare covers adults 65 and older and certain younger people with qualifying disabilities. It is divided into parts covering hospital care, outpatient services, and prescription drugs.
A low premium does not always mean lower total cost
What to check before choosing a plan
Before settling on a plan, confirm a few things that the premium alone will not tell you.
- Provider network: Check whether your current doctors and preferred hospitals are in-network. Switching providers mid-treatment can be disruptive.
- Drug formulary: If you take prescription medications, find out whether they appear on the plan's formulary and at what cost tier. The health coverage terms glossary explains how formulary tiers work.
- Total annual cost estimate: Add your expected premium payments to your estimated out-of-pocket spending based on how much care you typically use. Compare that total across plans, not just the monthly premium.
- Prior authorization requirements: Some plans require advance approval for certain procedures, specialist visits, or medications. Knowing this upfront prevents unexpected denials.
Health insurance decisions carry real financial weight. If the plan options feel overwhelming, a certified insurance navigator can walk you through your choices at no charge. Common mix-ups that lead to surprise bills is a useful next read once you have the basics in place.
This article is general information, not medical or financial advice
Frequently Asked Questions
The content provided on our blog site traverses numerous categories, offering readers valuable and practical information. Readers can use the editorial team’s research and data to gain more insights into their topics of interest. However, they are requested not to treat the articles as conclusive. The website team cannot be held responsible for differences in data or inaccuracies found across other platforms. Please also note that the site might also miss out on various schemes and offers available that the readers may find more beneficial than the ones we cover.