
A Homeowner's Introduction to Property Taxes
Photo: SmartGlobetrotter.net editorial
Key Takeaways
- Property taxes are set locally, so rates and rules vary significantly by county and state.
- Your bill is based on an assessed value, which may differ from your home's market price.
- Reassessments can happen after a sale, a renovation, or on a scheduled cycle.
- Many states offer exemptions that reduce the taxable value for eligible homeowners.
- You have the right to appeal an assessment you believe is inaccurate.
What property taxes are and why they exist
Property taxes are annual charges local governments levy on real estate. Counties, municipalities, and school districts use this revenue to fund public services: roads, schools, fire departments, and libraries. Because these services are local, property tax rates and rules are set at the county or municipal level, not by the federal government.
For most homeowners, property taxes are one of the largest recurring costs after mortgage payments. They continue for as long as you own the property, regardless of whether the mortgage is paid off. Understanding the mechanics behind your bill makes it easier to budget accurately and spot errors. The full picture of household costs also includes other recurring charges many owners miss until the bills arrive.
Assessed value
The dollar value a local government assigns to your property for tax purposes. It is often lower than the market price.
Mill rate
The tax rate expressed as dollars per $1,000 of assessed value. A mill rate of 10 means $10 in tax for every $1,000 of assessed value.
Homestead exemption
A reduction in a home's taxable value available to owners who use the property as their primary residence.
Escrow account
An account managed by your mortgage servicer that collects monthly tax and insurance payments and disburses them when bills are due.
Assessment appeal
A formal request to have your property's assessed value reviewed and potentially lowered by the local government.
How your property is assessed
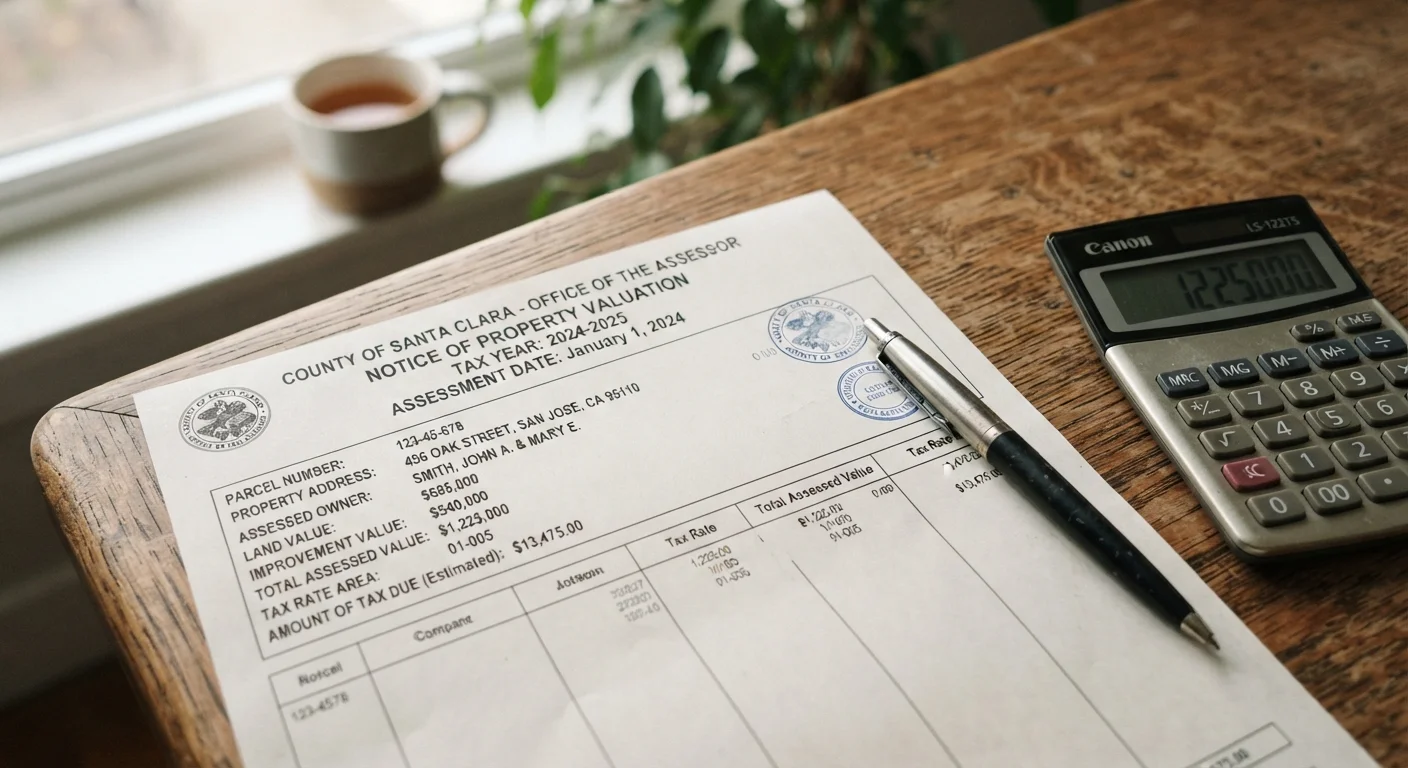
A county assessor assigns an assessed value to your property, which is the figure used to calculate your tax bill. This number is not always the same as market value. Many counties assess at a fixed percentage of market value, sometimes called the assessment ratio. If your home has a market value of $300,000 and the county uses an 80% assessment ratio, the assessed value is $240,000.
Assessors typically use comparable recent sales in your area, the replacement cost of the structure, and any income the property generates (for investment properties). The county mails an assessment notice each year or after a reassessment cycle, showing the new assessed value and the deadline to appeal.
How the tax bill is calculated
Once the assessed value is set, the local government applies the mill rate to produce your bill. A mill rate of 15 on an assessed value of $240,000 produces an annual tax of $3,600 (15 divided by 1,000, multiplied by $240,000). Most homeowners see a combined rate that layers the county levy, the municipal levy, and the school district levy on top of one another.
Your final bill may be lower if you qualify for exemptions, which are subtracted from the assessed value before the rate is applied. Without checking for available exemptions, some owners pay more than required.
When and how you pay
Payment schedules vary by state. Some jurisdictions send one annual bill; others split it into two or four installments due at set points in the year. Missing a deadline typically results in penalty interest, and extended nonpayment can lead to a tax lien on the property.
If your mortgage includes an escrow account, your servicer collects roughly one-twelfth of your estimated annual tax bill each month and pays the county directly. Your monthly mortgage statement will show the escrow portion separately. If the tax bill increases, your servicer adjusts the monthly escrow amount, which raises your total mortgage payment. Owners without an escrow arrangement pay the county directly and are responsible for setting aside funds throughout the year.
What can change your assessment
Three situations commonly trigger a change in assessed value. First, a sale: many counties reassess a property when ownership transfers, resetting the assessed value to reflect the purchase price. Second, permitted renovations or additions increase the property's value in the assessor's records. Third, scheduled mass reassessments, when a county revalues all properties at once, can raise or lower your assessed value based on shifts in local market conditions.
Broader market changes can cut both ways. A declining local market may reduce your assessed value; a rising market often increases it. If the increase seems out of step with actual conditions on your street, comparing your assessment to neighbors' can give you a starting point for an appeal. This is also worth considering alongside other ownership costs covered in the guide to overlooked household expenses.
Exemptions and appeals
Most states offer at least one exemption program. The homestead exemption is the most common: it reduces the taxable portion of assessed value for a primary residence. Other programs exist for seniors on fixed incomes, veterans, and homeowners with disabilities. Each program has its own income or eligibility thresholds, and most require a one-time application through the county assessor's office.
If you believe the assessed value is too high, you have the right to appeal. The process typically starts with an informal review, where you present recent comparable sales or an independent appraisal. If that does not resolve it, most counties have a formal appeals board. Act quickly: appeal windows are usually short, often 30 to 90 days from the notice date. Documenting the condition of your property and gathering sale prices of similar nearby homes gives an appeal its strongest foundation.
This article is for general informational purposes only and does not constitute financial, legal, or tax advice. Tax laws and assessment procedures vary by jurisdiction. Consult a licensed tax professional or attorney for guidance specific to your situation.
Frequently Asked Questions
The content provided on our blog site traverses numerous categories, offering readers valuable and practical information. Readers can use the editorial team’s research and data to gain more insights into their topics of interest. However, they are requested not to treat the articles as conclusive. The website team cannot be held responsible for differences in data or inaccuracies found across other platforms. Please also note that the site might also miss out on various schemes and offers available that the readers may find more beneficial than the ones we cover.