
What an Explanation of Benefits Actually Tells You (And What to Do With It)
Photo: SmartGlobetrotter.net editorial
Key Takeaways
- An EOB is a summary of a processed insurance claim, not a request for payment.
- It shows the billed amount, the insurer's allowed amount, what the plan paid, and what you may owe.
- Errors on EOBs are not rare; reviewing each one helps you avoid overpaying.
- If your EOB and the provider's bill don't match, contact both parties before paying.
- You can appeal a claim decision if you believe the insurer applied your benefits incorrectly.
Why the EOB exists and who sends it
Every time a health provider submits a claim to your insurer, your insurer processes it and then sends you a record of that decision. That record is the Explanation of Benefits. It comes from your insurance company, not your doctor's office or hospital.
The purpose is transparency. You are entitled to know what was billed on your behalf, what your plan agreed to pay, and what portion falls to you under your cost-sharing arrangement. For a broader look at how those cost-sharing pieces fit together, see how deductibles, copays, and coinsurance work.
Because the EOB can look like an invoice, many people set it aside thinking it is a duplicate of a bill they will receive. Treating it that way means missing one of the few chances you have to catch a billing or processing error before money changes hands.
What each section of an EOB means
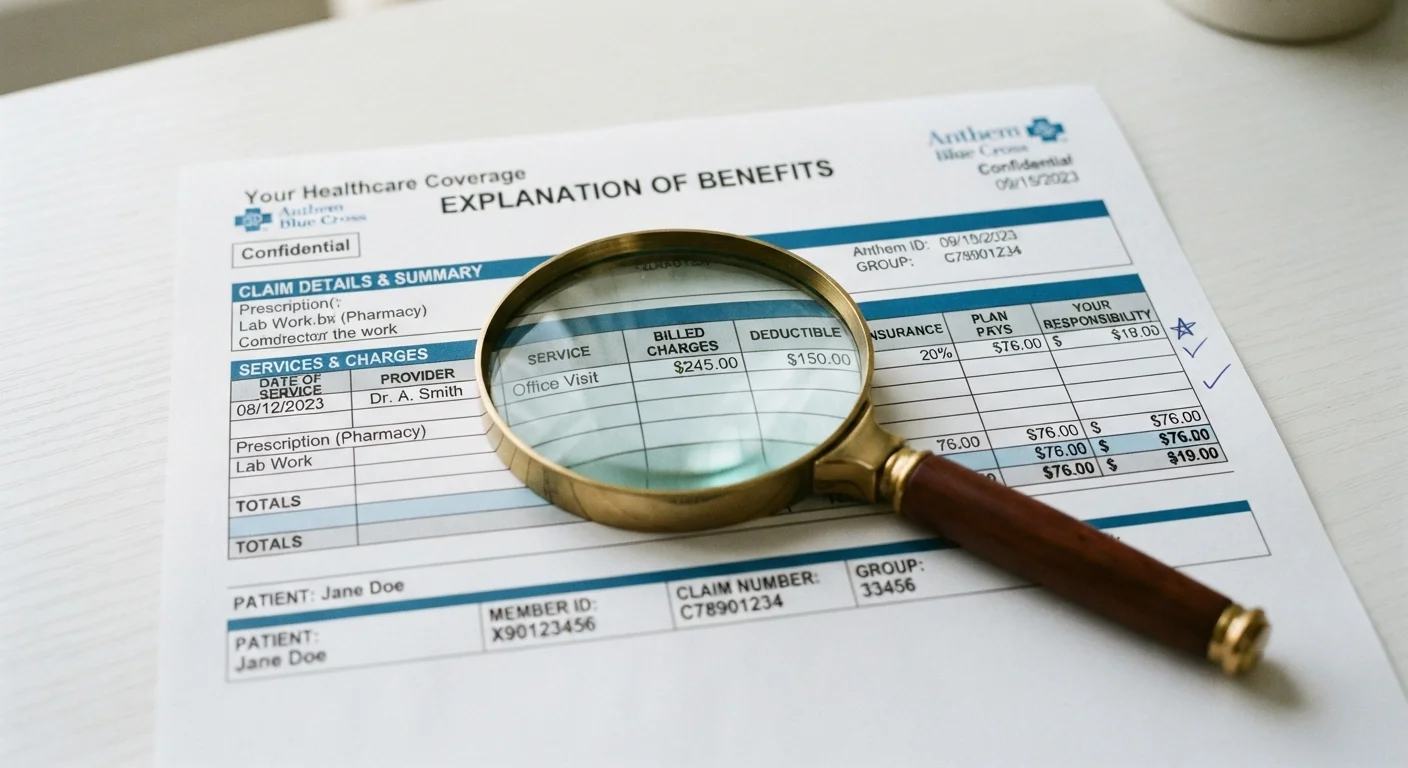
EOB layouts vary by insurer, but the core information appears in most versions.
The billed amount
This is what the provider charged for the service. It is almost always higher than what the insurer actually pays, because providers and insurers negotiate contracted rates.
The allowed amount
This is the maximum the insurer will recognize for that service under its contract or fee schedule. In-network providers agree to accept this figure and cannot bill you for the difference. Out-of-network providers may bill you for the gap between the billed amount and the allowed amount, sometimes called balance billing. In-network vs. out-of-network costs explains how provider status shapes what you ultimately owe.
Plan paid
This is the dollar amount the insurer paid directly to the provider after applying your plan's rules, including whether you have met your deductible and what coinsurance rate applies.
Your responsibility
This is the amount the EOB attributes to you. It combines any deductible portion, copay, or coinsurance for that claim. This figure should match, or come close to, what the provider's billing office later asks you to pay. If it does not match, that gap deserves investigation.
Claim status and reason codes
If a service was denied or only partially covered, the EOB includes a code or brief note explaining why. Common reasons are missing prior authorization, a service deemed outside plan benefits, or an out-of-network provider. These codes matter because they tell you the specific ground for appeal if you disagree with the decision.
EOBs are not always mailed
How to check an EOB for errors
Billing errors in health care are not unusual. A mistyped procedure code or a duplicate claim submission can inflate what appears as your responsibility.
When an EOB arrives, confirm four things: the date of service matches your actual visit, the provider name is the one you saw, the procedure or service described is what occurred, and the patient listed is actually you or your covered dependent. If any of these are wrong, call your insurer's member services line promptly. Most plans have a window, often 180 days from the claim date, within which errors can be corrected.
After reviewing the EOB, hold it until the provider's bill arrives. Compare the patient responsibility figures on both documents. If they differ, ask each party to explain the difference before sending any payment. Paying a bill that contradicts your EOB can complicate any subsequent dispute.
For a broader look at the coverage misunderstandings that lead to surprise costs, common health insurance misconceptions is worth reviewing alongside this process.
When to file an appeal
If the EOB shows a denial or a cost-sharing amount that does not match your plan's stated benefits, you have the right to appeal. Start by requesting the specific reason for the decision in writing if it is not already spelled out. Your insurer is required to provide this.
Gather supporting documentation: the referral or authorization if one was issued, any clinical notes your provider is willing to share, and the relevant section of your Summary of Benefits and Coverage. Submit a written appeal to your insurer within the timeframe the EOB specifies. Most plans allow at least 180 days from the date of the adverse decision for a first-level internal appeal.
If the internal appeal is unsuccessful, federal law gives you the right to an external review by an independent organization for most employer-sponsored and marketplace plans. Your EOB or your insurer's denial letter should explain how to request one.
Understanding your plan's overall structure helps frame any appeal. A plain-English walkthrough of health insurance covers the benefit structure behind the numbers that appear on your EOB.
This article is for general informational purposes only and is not a substitute for advice from a licensed insurance professional or qualified healthcare provider. Coverage terms, appeal rights, and timelines vary by plan. Review your plan documents and consult a licensed agent or adviser for guidance specific to your situation.
Frequently Asked Questions
The content provided on our blog site traverses numerous categories, offering readers valuable and practical information. Readers can use the editorial team’s research and data to gain more insights into their topics of interest. However, they are requested not to treat the articles as conclusive. The website team cannot be held responsible for differences in data or inaccuracies found across other platforms. Please also note that the site might also miss out on various schemes and offers available that the readers may find more beneficial than the ones we cover.