
Seven Things That Affect What You Actually Pay for Health Coverage
Photo: SmartGlobetrotter.net editorial
Key Takeaways
- Your monthly premium is only one of several costs that determine what you actually pay for health coverage.
- Where you live affects your premiums because insurers price plans based on local medical costs and market competition.
- Plan tier, household size, age, and tobacco use are all factored into your rate before any subsidies apply.
- Income-based subsidies on the ACA marketplace can significantly reduce what you owe each month.
- The plan you choose for its low premium may cost more overall if you use medical care regularly.
Why your health coverage costs what it does
When people shop for health coverage, the monthly premium tends to get most of the attention. That number is visible, easy to compare, and shows up in your bank account every month. But the premium alone does not tell you what you will actually spend on care in a given year. Several other variables shape that total, and some of them have nothing to do with the plan itself.
The factors below apply broadly to individual and family plans purchased through an employer, the ACA marketplace, or directly from an insurer. Coverage rules vary by plan type and state, so this article is general educational information, not personalized insurance or financial advice. A licensed insurance agent or broker can help you assess your specific situation.
Common mix-ups about health insurance can make these costs even harder to decode, so it helps to start with the variables themselves.
Plan metal tier
ACA-compliant plans are grouped into four metal tiers: Bronze, Silver, Gold, and Platinum. The tier describes how costs are split between you and the insurer over the course of a year, not the quality of care. Bronze plans carry the lowest monthly premiums and the highest deductibles. Platinum plans have the highest premiums and the lowest cost-sharing when you use care. Silver sits in the middle and is the only tier eligible for cost-sharing reduction subsidies if your income qualifies.
Choosing a tier is a judgment call about how much care you expect to use. If you use little care, a Bronze plan's lower premium may work in your favor. If you manage a chronic condition or take regular prescriptions, the lower cost-sharing of a Gold plan may reduce your total annual spending even though the monthly premium is higher.
The metal tier you choose determines how costs are split between you and the insurer all year.
Your age
Insurers in the individual market are allowed to charge older enrollees more than younger ones, within limits set by the ACA. The law caps that ratio at 3 to 1, meaning a 64-year-old cannot be charged more than three times what a 21-year-old pays for the same plan. Age-based pricing does not apply the same way to employer group plans, where premiums are typically based on the group as a whole rather than each individual's age.
This factor is fixed; you cannot change it. But it does mean that two people buying identical coverage in the same area will pay different premiums based solely on their age.
ACA rules limit age-based pricing, but older enrollees still pay more than younger ones for the same plan.
Where you live
Premiums vary considerably by state, and within states by county or rating area. Insurers price plans based on local medical costs, the number of competing insurers in the market, and provider contract rates in the area. Rural areas often have fewer insurers and narrower provider networks, which can push premiums higher.
Your ZIP code also determines which plans are available to you. Two people with identical incomes and ages living in different states can face very different premium ranges for comparable coverage.
Local medical costs and market competition directly influence what plans cost in your area.
Tobacco use
Under the ACA, insurers in the individual market may charge tobacco users up to 50% more than non-users, though some states have set lower limits or banned the surcharge entirely. This is assessed at the time of enrollment and is typically self-reported on the application.
The tobacco surcharge applies to premiums but not to premium tax credits, which means it falls entirely on the enrollee. In states that allow the full surcharge, the added cost can be substantial over the course of a year.
The tobacco surcharge is not offset by ACA subsidies, so the full added cost falls on the enrollee.
Household size and who you cover
If you are buying coverage for a family rather than just yourself, the number of people on the plan affects the premium. Each additional member adds cost, though family premiums are usually structured so that covering three or more children does not increase the child portion beyond what three children would cost.
Household size also matters for subsidy eligibility. The ACA's premium tax credits are calculated using a percentage of the federal poverty level, which accounts for how many people are in your household. A larger household at the same income level may qualify for a larger subsidy.
Household size affects both the base premium and your eligibility for income-based subsidies.
Your income and subsidy eligibility
If you buy coverage through the ACA marketplace, your household income relative to the federal poverty level determines whether you qualify for premium tax credits. These credits reduce your monthly premium directly. Under current rules, households at a wide range of income levels may be eligible, though the credit amount phases down as income rises.
Employer-sponsored coverage works differently. If your employer offers coverage considered affordable under ACA definitions, you generally cannot receive marketplace subsidies even if the plan's family coverage would cost more than a set share of your income. Understanding this boundary matters if you are evaluating whether to take employer coverage or shop on the marketplace.
Premium tax credits on the ACA marketplace can bring monthly costs down significantly for eligible households.
Network type and how you use care
The structure of your plan's provider network affects both what you pay and who you can see. HMO plans (Health Maintenance Organizations) generally require you to use in-network providers and get referrals from a primary care physician. PPO plans (Preferred Provider Organizations) allow more flexibility to see out-of-network providers, typically at a higher cost. HDHP plans (High-Deductible Health Plans) pair a lower premium with a higher deductible and are often paired with a Health Savings Account.
Your actual spending depends heavily on how often you use care and whether your providers are in-network. A plan with a low premium and a narrow network can produce high out-of-pocket costs if your preferred doctors or hospital are not included. Before enrolling, checking that your current providers participate in a plan's network is one of the most practical steps you can take.
Out-of-network care can produce large bills even in plans that look affordable on paper.
Putting the pieces together
No single factor determines your cost in isolation. A high-deductible plan with a low premium may make financial sense if you rarely need care, but the math shifts quickly if you have ongoing prescriptions or see specialists regularly. Understanding deductibles, copays, and coinsurance is a practical next step once you have a sense of which plans are in your price range.
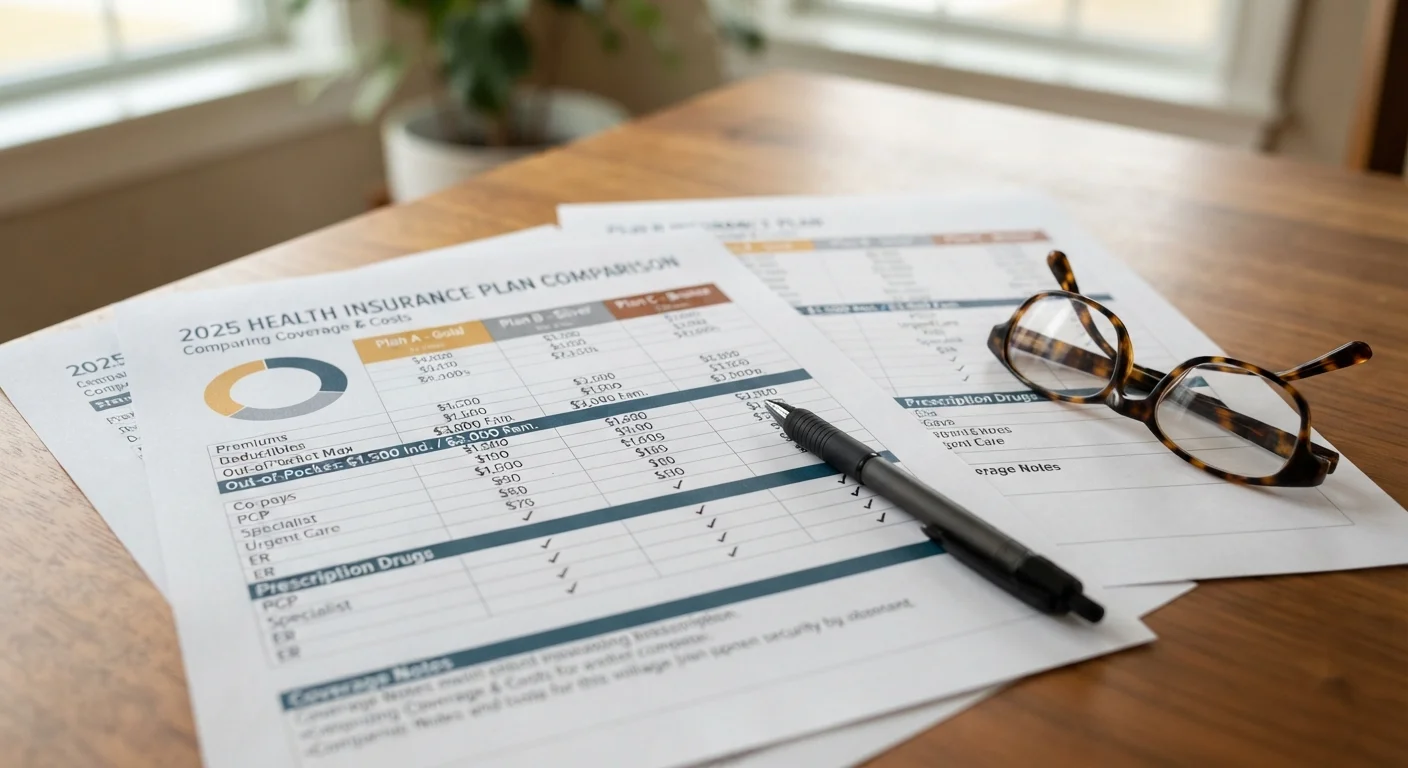
If you are approaching an open enrollment period, working through a checklist before switching plans can help you avoid losing access to your doctors or facing costs you did not anticipate. For unfamiliar terms in any plan documents you receive, a plain-language glossary of health coverage terms covers the vocabulary most shoppers encounter.
This article is for general informational purposes only and does not constitute insurance, financial, or medical advice. Coverage terms, eligibility rules, and costs vary by plan, insurer, and state. Consult a licensed insurance professional for guidance specific to your situation.
The content provided on our blog site traverses numerous categories, offering readers valuable and practical information. Readers can use the editorial team’s research and data to gain more insights into their topics of interest. However, they are requested not to treat the articles as conclusive. The website team cannot be held responsible for differences in data or inaccuracies found across other platforms. Please also note that the site might also miss out on various schemes and offers available that the readers may find more beneficial than the ones we cover.