
Questions to Ask Before Switching Health Plans During Open Enrollment
Photo: SmartGlobetrotter.net editorial
Why this checklist matters
Open enrollment comes around once a year for most people with employer-sponsored coverage or Marketplace plans. Switching health plans can lower your costs or better match your care needs, but it can also disrupt access to your doctors, raise your out-of-pocket spending, or leave your prescriptions uncovered if you move without checking the details first.
This checklist walks through the questions worth answering before you finalize any switch. If you are new to how health coverage works, this plain-English walkthrough covers the fundamentals before you compare plans. For a full step-by-step guide to the enrollment process itself, see this open enrollment walkthrough.
Switching plans mid-year outside open enrollment is limited
The checklist
Work through each group before making your decision. You will need your current plan documents, a list of your medications, and the names of any providers you want to keep seeing.
Current plan's Summary of Benefits and Coverage (SBC)
Use it to compare your existing plan's costs and rules against any new plan side by side.
Complete medication list
Match each prescription against the new plan's formulary to check coverage tier and cost.
Provider directory for the new plan
Confirm your doctors, specialists, and hospital are in-network before you switch.
Explanation of Benefits (EOB) from the past year
Review what you actually paid for care to estimate likely costs under a new plan structure.
Your care needs
Provider and network access
Prescription drug coverage
Cost structure
Enrollment timing and documentation
Reading the numbers carefully
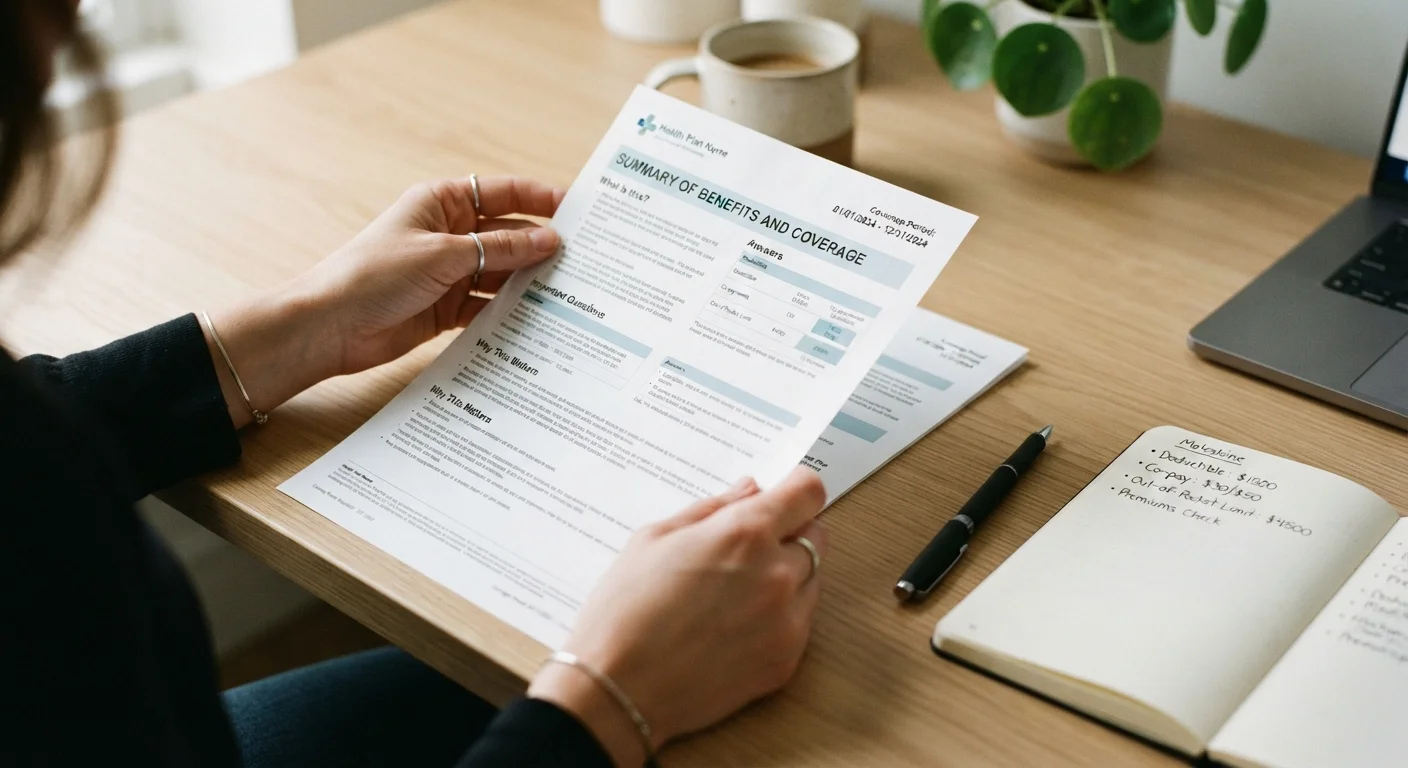
Premium is the amount you pay each month regardless of whether you use care. Deductible is what you pay out of pocket before your plan starts covering most services. Out-of-pocket maximum is the most you would pay in a calendar year before the plan covers 100 percent of covered costs. These three numbers together, not any one alone, shape what you actually spend.
Several factors affect your total health coverage costs, including where you live, which plan tier you choose, and whether your employer contributes to your premium. A common mistake is treating the lowest premium as the lowest-cost plan, which is rarely true for people who use care regularly.
If you are approaching Medicare age or already enrolled, costs during that transition can come with separate surprises. Costs that catch seniors off guard during Medicare enrollment covers those specifics.
This article is for general informational purposes only and is not a substitute for personalized advice from a licensed insurance professional. Plan details, costs, and coverage rules vary by provider and by state. Review the actual plan documents and consult a licensed agent or benefits administrator before making enrollment decisions.
The content provided on our blog site traverses numerous categories, offering readers valuable and practical information. Readers can use the editorial team’s research and data to gain more insights into their topics of interest. However, they are requested not to treat the articles as conclusive. The website team cannot be held responsible for differences in data or inaccuracies found across other platforms. Please also note that the site might also miss out on various schemes and offers available that the readers may find more beneficial than the ones we cover.