
Open Enrollment: A Step-by-Step Walkthrough for Picking a Health Plan
Photo: SmartGlobetrotter.net editorial
Key Takeaways
- Open enrollment is a limited annual window; missing it typically locks you into your current plan for another year.
- Your total health care cost includes more than the monthly premium: deductibles, copays, and out-of-pocket maximums all matter.
- Checking that your doctors and prescriptions are covered under a new plan before you enroll can prevent costly surprises.
- Subsidies through the federal or state Marketplace may reduce your monthly premium if your income qualifies.
- Life changes such as marriage, job loss, or a new child may open a Special Enrollment Period outside the standard window.
Why the steps matter before you click 'enroll'
Open enrollment is a time-limited process, and the choices you make have financial consequences for the full year ahead. Most people spend less than 30 minutes selecting a health plan, often defaulting to what they had before or choosing the lowest monthly premium. Both approaches can cost more in the long run.
The steps in this guide move from confirming your window to completing enrollment. Each one builds on the last. Skipping ahead, particularly past the doctor and drug verification steps, is where costly surprises tend to begin.
What you will need
If you are new to health insurance altogether, the plain-English walkthrough for first-timers covers the foundational terms and structures before you begin comparing plans.
How to work through each step
Confirm your enrollment window
Open enrollment dates vary by coverage type. For job-based coverage, your employer sets the window, typically in the fall. For Marketplace plans through healthcare.gov or a state exchange, the federal window generally runs from November 1 through January 15, though some states extend or shift these dates. Medicare's Annual Enrollment Period runs October 15 through December 7 each year.
Write your deadline on a calendar. Missing it means staying on your current plan for another year unless a qualifying life event triggers a Special Enrollment Period.
Review what your current plan actually cost you
Pull your Explanation of Benefits statements from the past 12 months. Add up what you paid in premiums, deductibles, copays, and coinsurance. This total, not just the monthly premium, is your real baseline. If you rarely used medical services, a lower-premium, higher-deductible plan may cost less overall. If you had several doctor visits, specialist referrals, or filled multiple prescriptions, a plan with richer benefits and a higher premium may have saved you money.
List your expected health care needs for the coming year
Think through any anticipated changes: a planned surgery, a new specialist, a pregnancy, or a child aging off your plan. Write down every prescription you take regularly. These specifics will determine which plan categories make sense for you and which networks you cannot afford to leave.
Understand the cost structure of each plan type
Health plans generally fall into a few network and cost-sharing structures. An HMO (Health Maintenance Organization) requires you to use in-network providers and usually needs a primary care referral to see a specialist. A PPO (Preferred Provider Organization) gives you more flexibility to see out-of-network providers, typically at higher cost. An EPO (Exclusive Provider Organization) limits you to the network but usually skips referral requirements. An HDHP (High-Deductible Health Plan) has a higher deductible in exchange for a lower premium and eligibility to open an HSA.
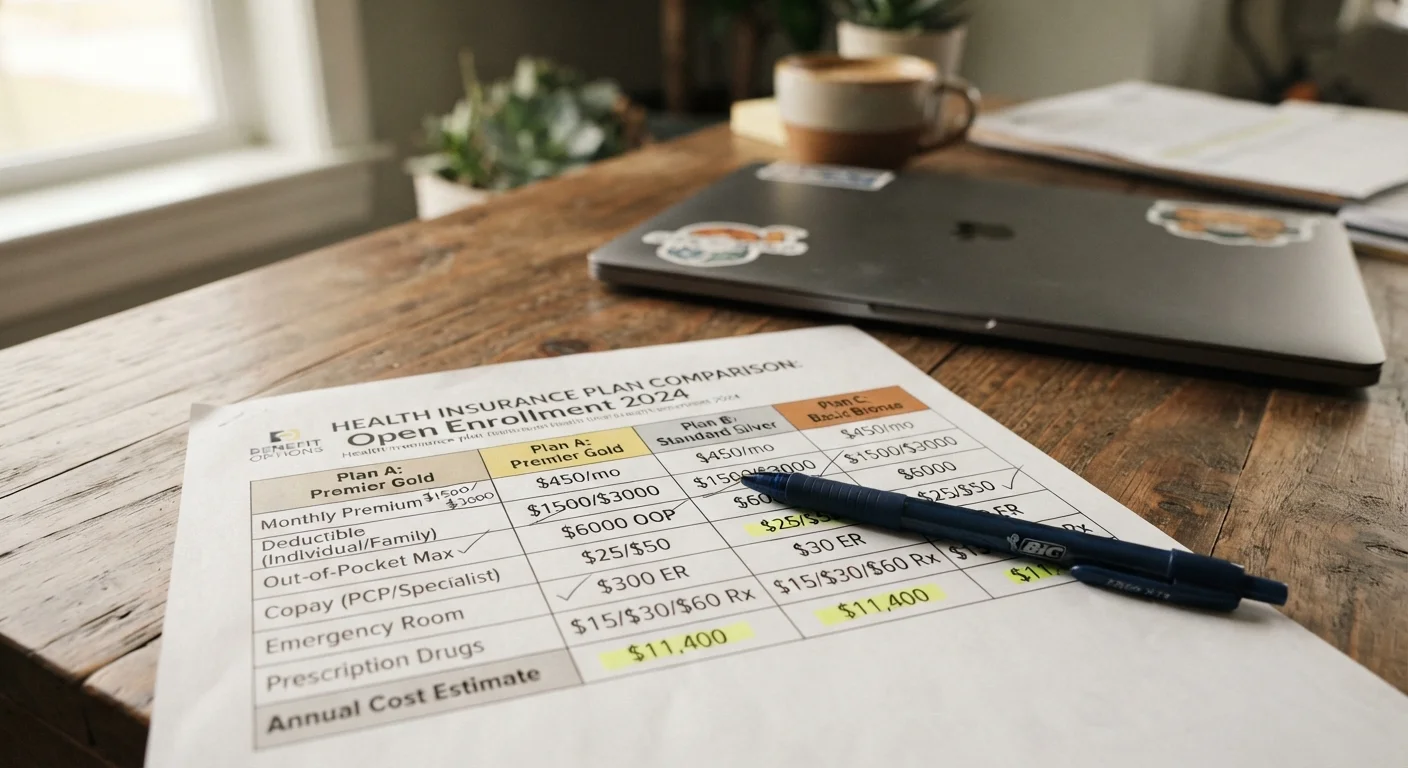
For each plan you consider, note the monthly premium, deductible, copay or coinsurance for office visits and specialist care, and the out-of-pocket maximum (the most you would pay in a calendar year before the plan covers 100 percent).
Check that your doctors and drugs are covered
Look up each plan's provider directory and confirm your primary care doctor, any specialists you see regularly, and your preferred hospital are listed as in-network. Then open the plan's drug formulary and locate each medication you take. Formularies group drugs into tiers, and your cost varies significantly by tier. A medication that costs $15 per month on your current plan could cost $80 or more on a new one if it sits in a higher tier.
Check whether you qualify for financial assistance
If you are enrolling through the federal Marketplace or a state exchange, your household income relative to the federal poverty level determines whether you qualify for premium tax credits (subsidies) that reduce your monthly cost, or for cost-sharing reductions that lower your deductibles and copays. Enter your income on the Marketplace application to see what you qualify for before comparing plan prices. Medicaid and the Children's Health Insurance Program (CHIP) are also available year-round for households that meet income thresholds.
Compare your shortlisted plans on total cost, not just premium
For each plan you are seriously considering, estimate a realistic annual cost. Multiply the monthly premium by 12, then add your expected out-of-pocket spending based on typical use. Run a best-case scenario (minimal care) and a worst-case scenario (hitting the out-of-pocket maximum). The plan with the lowest premium is not always the least expensive when you account for how often you actually use care.
If you are weighing a job change or thinking about switching plans, the checklist for switching health plans can help you avoid common gaps in coverage.
Enroll before the deadline
Once you have chosen a plan, complete enrollment through your employer's portal, healthcare.gov, or your state Marketplace. Print or save your confirmation and enrollment ID. Keep a copy of the plan's Summary of Benefits and Coverage for reference throughout the year.
Special Enrollment Periods to know about
Seniors navigating Medicare have a separate enrollment structure and timeline. The costs that commonly catch Medicare enrollees off guard covers late-enrollment penalties and Part B premiums that are worth understanding before the Medicare Annual Enrollment Period closes. A broader reference covering Medicare, Medicaid, and other senior benefits is available at the end-to-end senior benefits resource.
Auto-renewal does not mean best fit
This article is general information, not personal advice
This article provides general health insurance information for educational purposes only. It is not a substitute for advice from a licensed insurance professional. Coverage terms, costs, and eligibility requirements vary by plan, employer, and state. Always review official plan documents and consult a qualified agent or navigator before making enrollment decisions.
The content provided on our blog site traverses numerous categories, offering readers valuable and practical information. Readers can use the editorial team’s research and data to gain more insights into their topics of interest. However, they are requested not to treat the articles as conclusive. The website team cannot be held responsible for differences in data or inaccuracies found across other platforms. Please also note that the site might also miss out on various schemes and offers available that the readers may find more beneficial than the ones we cover.