
Costs That Catch Seniors Off Guard During Medicare Enrollment
Photo: SmartGlobetrotter.net editorial
Key Takeaways
- Missing your Initial Enrollment Period can trigger a permanent late-enrollment penalty on Part B premiums.
- Part B premiums are not fixed; higher earners pay more through income-related adjustments called IRMAA.
- Most Medicare plans carry deductibles, copays, and coinsurance that add up well beyond the monthly premium.
- Assuming current employer coverage exempts you from enrolling can lead to costly gaps if the rules are misunderstood.
- Part D drug coverage has its own late-enrollment penalty that compounds monthly for as long as you have Medicare.
Why Medicare costs surprise so many new enrollees
Medicare is often described as the health coverage you get at 65, but that description skips most of the financial detail that matters. The program has four main parts, multiple enrollment windows with permanent penalties attached, and a premium structure that varies by income. People who spend little time researching before their 65th birthday often face costs they did not anticipate.
This article covers the specific mistakes that produce those surprises, why they happen, and what to do differently. For a broader view of the full benefit landscape, the Medicare and senior benefits complete resource covers each program in detail.
This article is for general informational purposes only and is not personalized financial, insurance, or legal advice. Consult a licensed insurance counselor or benefits adviser for guidance specific to your situation.
Enrolling late because you assumed you had more time than the rules allow.
Treating the monthly premium as the total cost of coverage.
Not accounting for IRMAA when projecting Medicare costs.
Skipping Part D because you do not currently take prescription drugs.
Assuming active employer coverage automatically delays all Medicare enrollment without confirming the rules.
Enrollment windows, penalties, and income surcharges
The five mistakes above share a common thread: the cost consequences are not obvious until they appear on a bill or a Social Security statement. Penalties compound over time, income surcharges arrive based on tax data from two years earlier, and cost-sharing obligations only become visible when a claim is filed.
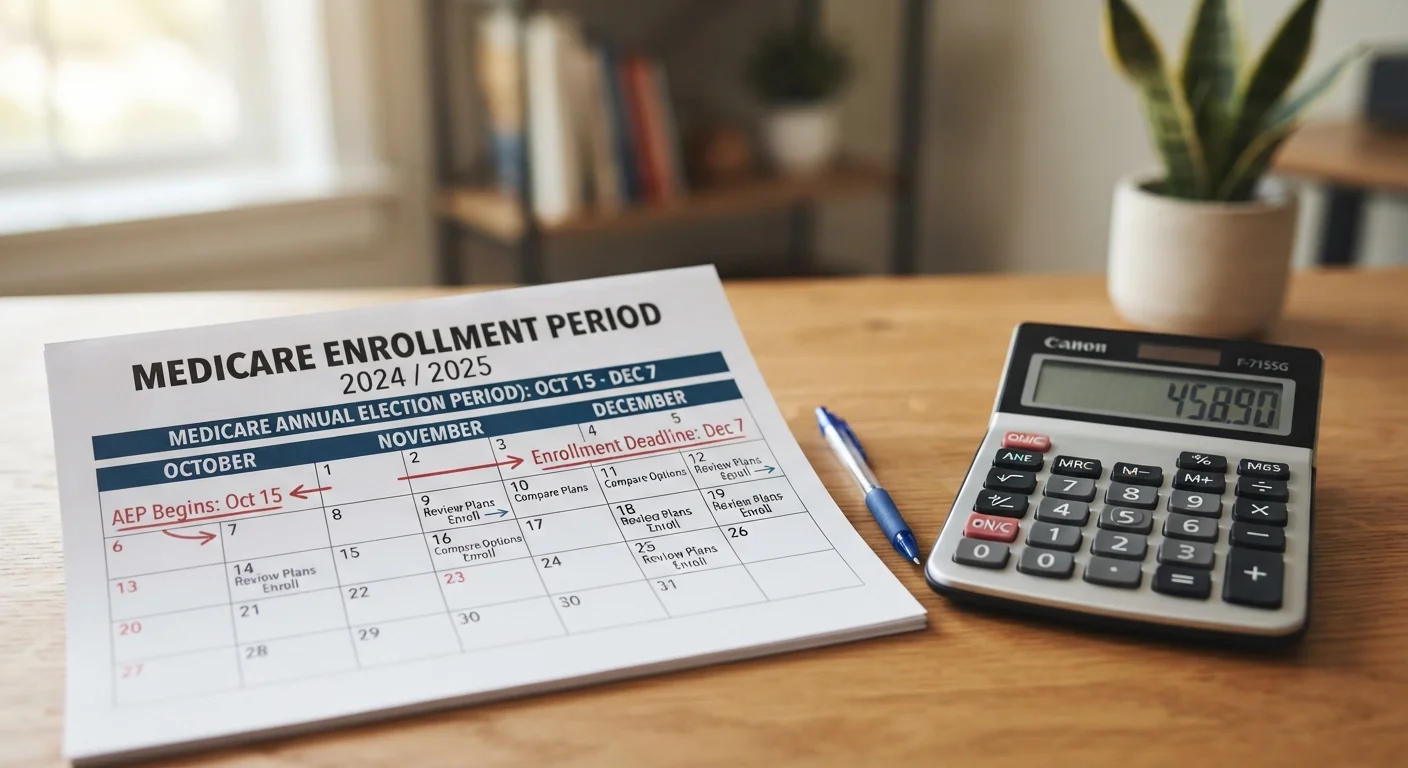
Reviewing the full plan details before committing matters as much as checking the premium. The open enrollment step-by-step walkthrough offers a practical framework for comparing plan structures beyond the monthly cost. If you are weighing a plan change in subsequent years, the questions to ask before switching health plans checklist addresses what to verify before making a move.
10%
Part B late-enrollment penalty per year uncovered
Medicare adds 10% to your Part B premium for each full 12-month period you were eligible but did not enroll, and this surcharge is permanent.
1%
Part D penalty per uncovered month
The Part D late-enrollment penalty equals 1% of the national base beneficiary premium for each month without creditable coverage, compounding over your enrollment lifetime.
$240+
Part A hospital deductible per benefit period
As of 2024, the Part A inpatient deductible exceeded $1,600 per benefit period; this figure changes annually. Check Medicare.gov for the current amount.
The content provided on our blog site traverses numerous categories, offering readers valuable and practical information. Readers can use the editorial team’s research and data to gain more insights into their topics of interest. However, they are requested not to treat the articles as conclusive. The website team cannot be held responsible for differences in data or inaccuracies found across other platforms. Please also note that the site might also miss out on various schemes and offers available that the readers may find more beneficial than the ones we cover.