
Finance

Managing Money on a Fixed Income: Practical Approaches for Seniors
Managing Money on a Fixed Income: Practical Approaches for Seniors

Photo: SmartGlobetrotter.net editorial

General strategies for stretching a fixed income, understanding benefit timing, and keeping essential expenses manageable in retirement.

Key Takeaways

  • A written monthly budget is the foundation of managing any fixed income successfully.
  • Social Security timing and benefit coordination can affect your total monthly income for years.
  • Assistance programs such as Medicare Savings Programs and SNAP can lower essential expenses.
  • Separating needs from discretionary spending helps when income does not change month to month.
  • A licensed financial adviser can help you make decisions suited to your specific situation.

Why fixed-income budgeting is different

When income comes from Social Security, a pension, or required minimum distributions from a retirement account, it arrives in predictable amounts on predictable dates. That predictability is useful, but it also means there is no overtime pay or bonus to absorb an unexpected expense. Every dollar of outflow needs to be planned in advance.

The challenge compounds because several major costs in retirement, particularly housing, healthcare, and utilities, tend to rise over time while monthly benefit amounts adjust more slowly. Understanding that gap is the starting point for building a spending plan that holds.

For a broader foundation on budgeting mechanics, the month-to-month budgeting guide walks through how to build and maintain a realistic spending plan at any income level.

Practical approaches for stretching a fixed income

1

List every income source and its exact monthly amount before building any spending plan

Fixed-income budgets fail most often because one or two income streams are forgotten or estimated loosely. Knowing the precise total arriving each month sets a hard ceiling for spending commitments. This step also reveals whether income arrives in one lump or across several dates, which affects how you time bill payments.
Example: A retiree receiving Social Security on the second Wednesday of each month and a pension deposit on the first of the month maps both dates on a calendar before assigning any bill due dates.
2

Separate non-negotiable expenses from variable ones and cover non-negotiables first

Rent or mortgage, utilities, insurance premiums, and prescription costs cannot be deferred without serious consequences. Treating these as fixed commitments paid at the start of each cycle prevents shortfalls from crowding out essential needs. What remains after those obligations is what can flex.
Example: After listing all fixed obligations, a household finds $340 per month available for groceries, transportation, and personal spending, and sets informal caps for each category.
3

Review subscription and recurring charges at least twice a year

Streaming services, club memberships, and auto-renewing software licenses often continue charging long after the service stops being used. On a fixed income, each unused charge reduces the buffer available for genuine needs. A periodic review catches these before they accumulate.
Example: A quarterly calendar reminder prompts a retiree to open their bank statement and cancel two streaming subscriptions and a roadside-assistance plan they duplicated through their auto insurance.
4

Build a small cash buffer before retirement begins, even if income seems sufficient

Irregular expenses such as a car repair, a dental bill, or a home appliance replacement arrive without warning. Without a buffer, fixed-income households often turn to credit cards, which adds interest costs to an already tight budget. Even a modest reserve of one or two months of non-negotiable expenses reduces that risk.
Example: A person retiring in six months redirects $150 per month for the remaining months into a separate savings account earmarked only for irregular essential expenses.
5

Understand Social Security timing before claiming

Claiming Social Security at 62 reduces the monthly benefit permanently compared to waiting until full retirement age or later. The difference compounds over decades. While personal health, employment status, and other income sources all affect the right timing, understanding the trade-off before claiming prevents a decision that cannot be reversed.
Example: Someone considering early claiming at 62 calculates how the reduced monthly amount compares to waiting until 67, then discusses the scenario with a financial adviser before filing.
6

Check eligibility for income-based assistance programs each year

Eligibility thresholds for programs such as Medicare Savings Programs, SNAP, and state pharmaceutical assistance programs change periodically. A household that did not qualify two years ago may qualify now, particularly after a spouse's income changes or medical costs rise. Annual checks cost nothing and can meaningfully lower essential expenses.
Example: After a spouse passes and household income drops, a senior contacts their State Health Insurance Assistance Program (SHIP) counselor to review updated Medicare Savings Program eligibility.

This article provides general financial information for educational purposes only. It is not personalized financial, tax, or legal advice. Consult a licensed financial adviser, accountant, or attorney before making decisions about your specific situation.

Benefit programs that reduce essential costs

Several federal and state programs exist specifically to lower out-of-pocket costs for lower-income seniors. Medicare Savings Programs, for example, can help cover Part B premiums and cost-sharing amounts. The Supplemental Nutrition Assistance Program (SNAP) has eligibility rules that apply to seniors with limited income and assets. Low Income Home Energy Assistance Program (LIHEAP) funds can offset heating and cooling bills.

Eligibility rules vary by program and by state, and income thresholds are updated periodically. The overview of federal and state benefit programs explains how these programs generally work and how to start checking eligibility.

For Medicare-specific coverage questions, the Medicare and senior benefits resource covers program structures and enrollment considerations in detail.
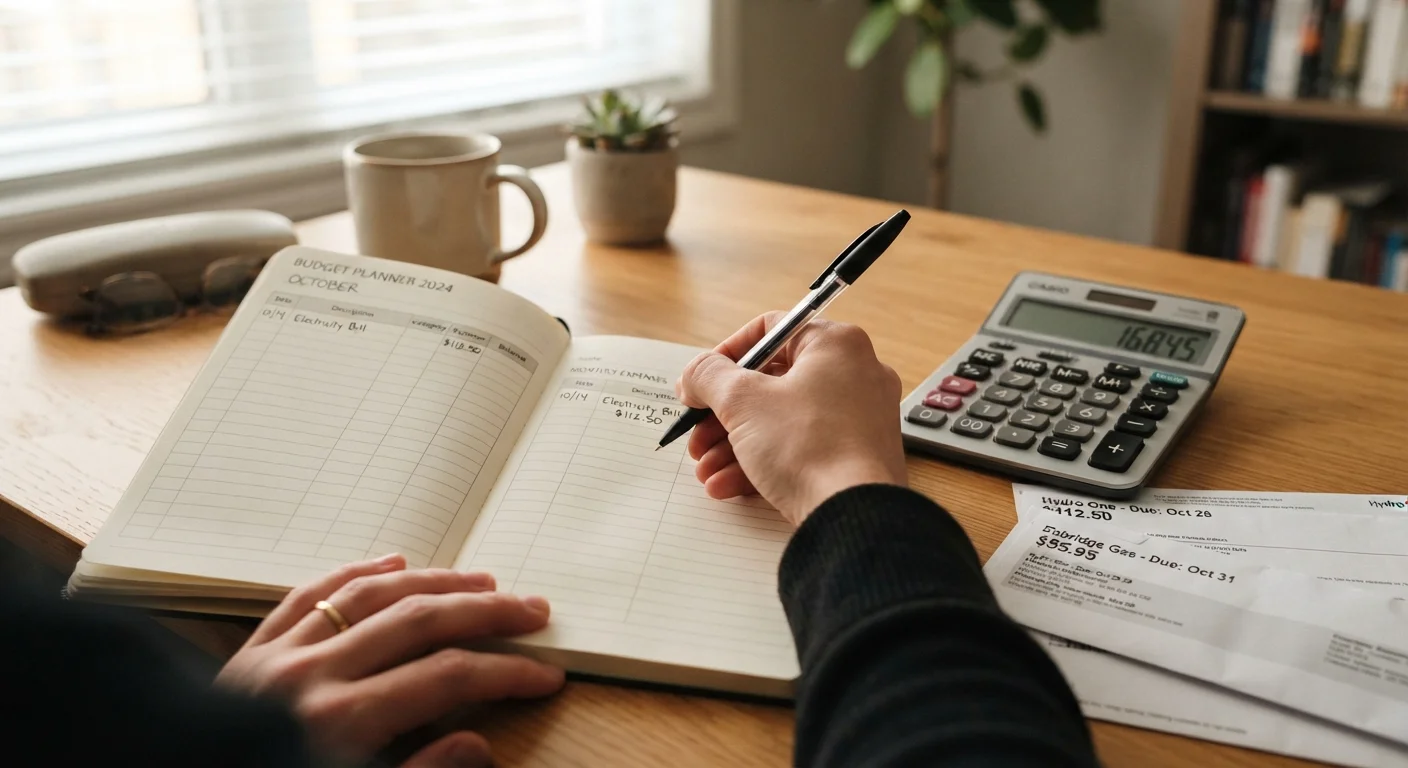
Hand writing in a budget planner notebook with utility bills and calculator nearby
Tracking spending by category each month makes it easier to spot where adjustments are possible.

Quick actions to take now

medium Pull three months of bank and credit card statements today and total every recurring charge. Cancel any you cannot immediately identify as actively used.
high Call your local Area Agency on Aging (find it at eldercare.acl.gov) to ask about benefit enrollment assistance available in your county.
high Write down every income source, the exact amount, and the date it arrives each month. Use that list as the first page of your budget.
medium Ask your pharmacy whether a generic version is available for each prescription you fill regularly. Confirm with your prescribing doctor before switching.

Housing is often the largest single line item on a fixed income. If you are weighing whether your current living situation still fits your budget, the comparison of aging in place versus senior communities lays out the financial and practical trade-offs without steering toward one path.

Small spending habits can also erode a budget before they become visible. The article on habits that undermine household budgets covers patterns that are easy to overlook on a month-to-month basis.

Finance Editorial Team

SmartGlobetrotter.net

Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.

Finance
View author profile

The content provided on our blog site traverses numerous categories, offering readers valuable and practical information. Readers can use the editorial team’s research and data to gain more insights into their topics of interest. However, they are requested not to treat the articles as conclusive. The website team cannot be held responsible for differences in data or inaccuracies found across other platforms. Please also note that the site might also miss out on various schemes and offers available that the readers may find more beneficial than the ones we cover.