
Travel Insurance for Seniors: Key Considerations Before You Buy
Photo: SmartGlobetrotter.net editorial
Why seniors face different coverage needs
Standard travel insurance policies are built around common traveler risks: canceled flights, lost bags, and minor medical mishaps. For older adults, the financial stakes around medical coverage are often much higher. Medicare generally does not pay for health care received outside the United States, and Medicare Supplement plans vary widely in what international coverage they include. A detailed look at those gaps is available in our article on what Medicare does not cover.
Because of this coverage gap, travel medical insurance is often the most financially significant component of a senior's travel insurance decision, not trip cancellation or baggage protection. Travelers managing healthcare costs on a fixed budget may find the analysis in managing money on a fixed income useful alongside the insurance planning process.
| Medicare overseas coverage | Generally not covered outside the U.S. (Medicare.gov) |
| Typical CFAR reimbursement rate | 50% to 75% of prepaid non-refundable costs |
| Common pre-existing waiver purchase window | 14 to 21 days from first trip deposit |
| Air evacuation cost range | Can exceed $100,000 for long-distance transport |
| Typical look-back periods | 60, 90, or 180 days depending on the policy |
Pre-existing conditions: what to know before you shop
Most travel insurance policies contain a pre-existing condition exclusion by default. This means that a medical event related to a condition diagnosed before the policy was purchased may not be covered. However, many policies offer a waiver that removes this exclusion if certain conditions are met.
Waivers typically require that you purchase the policy within a set window after your first trip deposit, often 14 to 21 days, and that you are medically able to travel on the purchase date. Reading the exact definition of 'pre-existing condition' in any policy matters: some definitions look back 60 days, others 180 days, and the difference affects what qualifies.
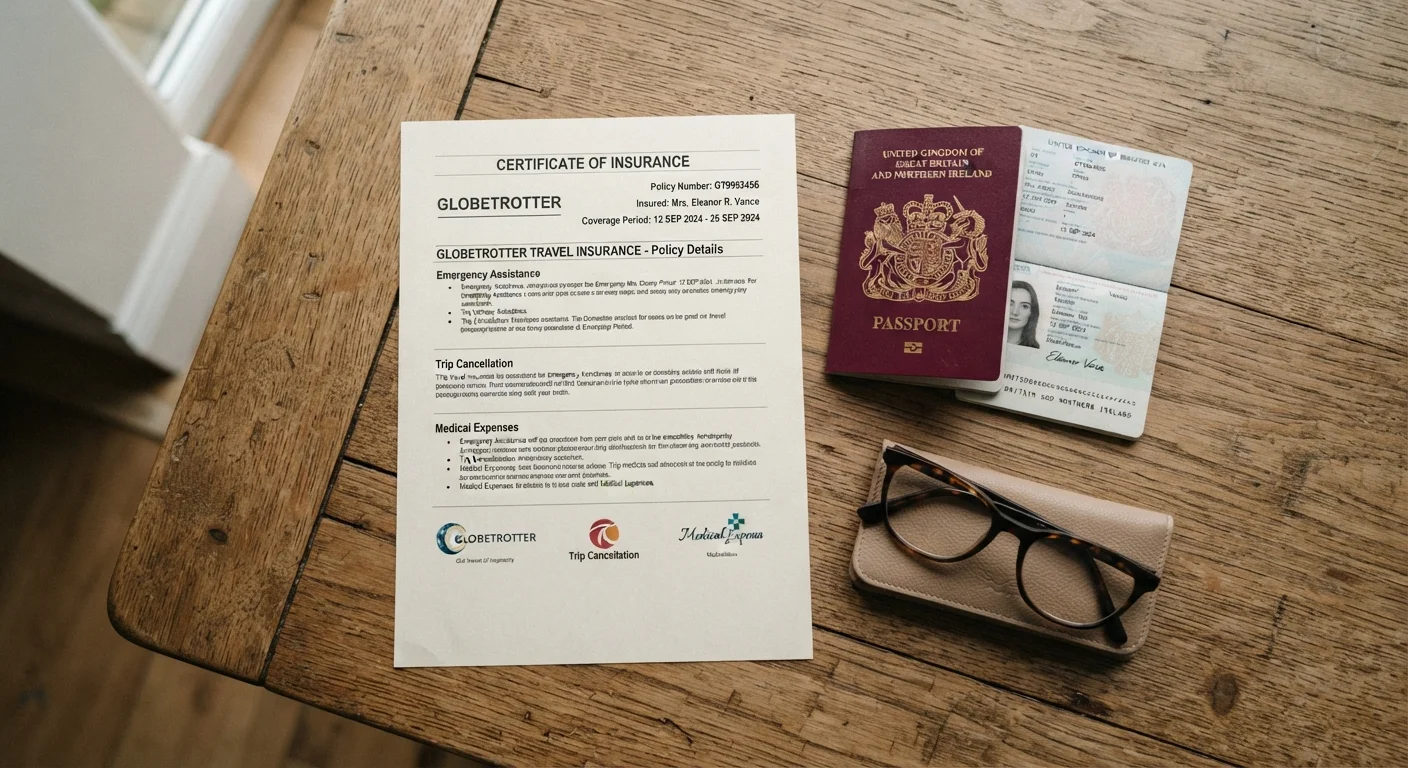
For travelers with conditions managed through multiple medications or recent hospitalizations, getting the waiver is usually worth the effort. Without it, a cardiac event, a COPD flare, or a diabetes complication abroad could result in a denied claim for tens of thousands of dollars in emergency care.
Medical evacuation coverage
Emergency medical evacuation transports you from a foreign hospital to one where you can receive adequate care, or back home. Costs for air evacuation can reach $100,000 or more depending on distance and medical need. Most basic travel policies include evacuation, but coverage limits vary. A policy with a $50,000 evacuation limit may be insufficient for a traveler in a remote location or on a cruise far from a major port city.
Confirm that the policy covers evacuation to your home hospital or to the nearest adequate facility. Some policies limit coverage to the nearest adequate facility, which may not be in the United States. This distinction matters for anyone with an established care team at home managing a chronic condition. For context on how supplemental health coverage works alongside primary insurance, the overview of Medigap supplement plans explains the general logic of layered coverage.
Trip cancellation and the 'cancel for any reason' add-on
Standard trip cancellation coverage reimburses prepaid, non-refundable costs if you cancel for a covered reason, typically illness, injury, or death of a traveler or close family member. The full list of covered reasons appears in the policy's definitions section and varies by plan. Our breakdown of how travel cancellation coverage works explains the specific triggers and reimbursement rules in plain terms.
A 'cancel for any reason' (CFAR) upgrade lets you cancel for reasons not listed in the standard policy and typically reimburses 50% to 75% of prepaid costs. CFAR adds to the premium and usually must be purchased within the same early window as the pre-existing condition waiver. For seniors who may face shifting health circumstances in the months before a trip, CFAR can provide flexibility that standard coverage does not.
This article is for general informational purposes only and does not constitute insurance, financial, or medical advice. Coverage terms, exclusions, and eligibility vary by policy and provider. Review actual policy documents carefully and consult a licensed insurance professional before making coverage decisions.
The content provided on our blog site traverses numerous categories, offering readers valuable and practical information. Readers can use the editorial team’s research and data to gain more insights into their topics of interest. However, they are requested not to treat the articles as conclusive. The website team cannot be held responsible for differences in data or inaccuracies found across other platforms. Please also note that the site might also miss out on various schemes and offers available that the readers may find more beneficial than the ones we cover.