
Senior

Moving a Parent Into Assisted Living: A Family Planning Checklist
Moving a Parent Into Assisted Living: A Family Planning Checklist

Photo: SmartGlobetrotter.net editorial

A practical checklist covering finances, care assessments, legal documents, and logistics to help families navigate an assisted living transition.

Key Takeaways

  • Confirming legal documents are in place before a move prevents delays in care decisions.
  • Medicaid eligibility rules for assisted living vary by state and require early planning.
  • A written care assessment from the community should be reviewed against your parent's actual needs.
  • Canceling or transferring household services and subscriptions is a detail many families overlook.
  • Consulting a licensed elder law attorney and a financial adviser is advisable before signing contracts.

Before you begin: what this checklist covers

Moving a parent into assisted living involves medical, financial, legal, and logistical decisions that often happen at the same time. This checklist organizes those tasks into manageable groups so nothing falls through the gaps. It is general information, not legal, financial, or medical advice. For decisions specific to your family's situation, consult a licensed elder law attorney, a financial adviser, and your parent's physician.

If your family is still weighing whether assisted living is the right path, see aging in place vs. moving to a senior community for a balanced look at the trade-offs before committing to a move.
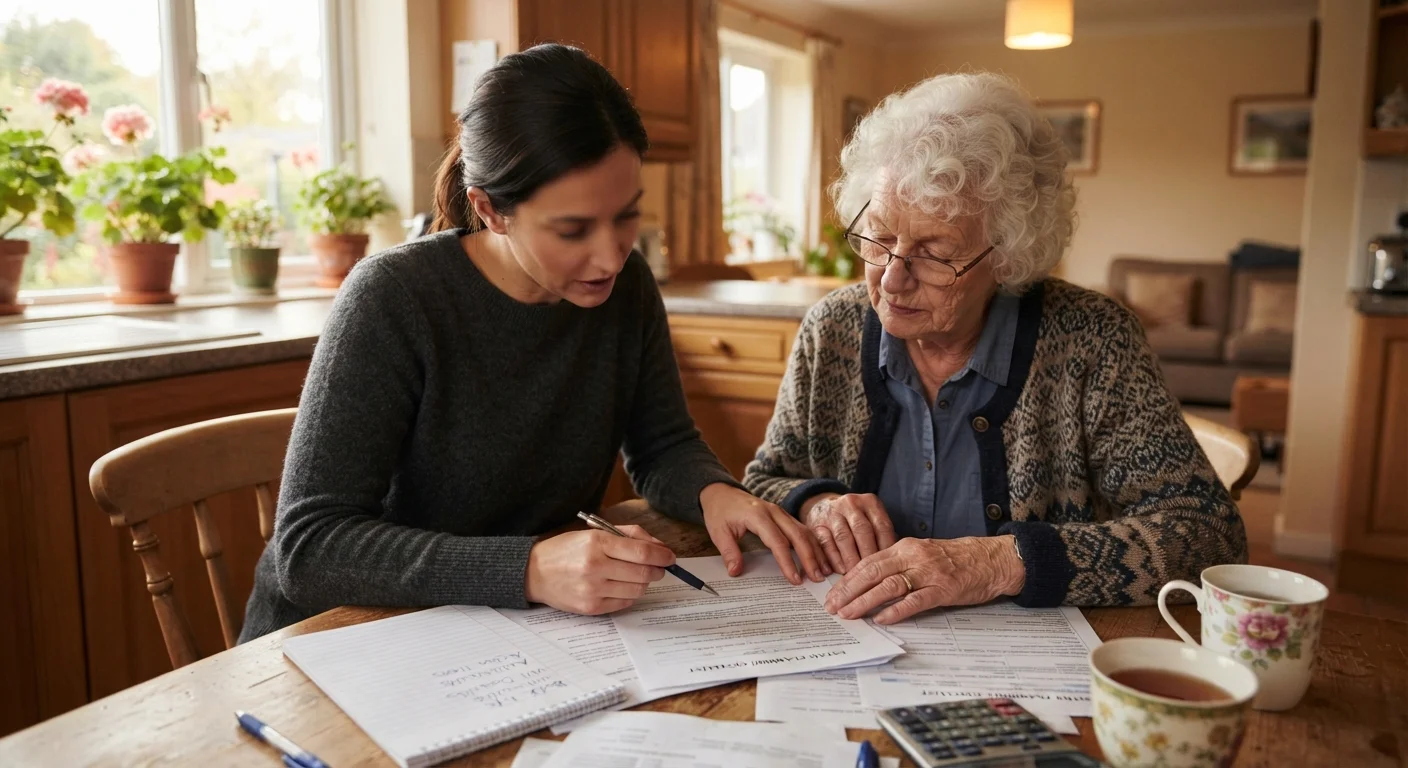
An adult child and an older parent reviewing assisted living paperwork together at a kitchen table.
Going through documents as a family helps ensure nothing is missed before the transition.

The planning checklist

Work through each group below. Items marked must are non-negotiable steps; should items are strongly recommended; nice to have items add convenience but are not required for a safe transition.

Legal documents

Confirm a durable power of attorney for finances is signed and accessible, so a designated family member can manage accounts if your parent cannot. See key legal documents for seniors for a full list of what should be in place. Must
Verify a healthcare proxy or durable power of attorney for healthcare names the correct person and reflects your parent's current wishes. Must
Review the advance directive or living will to confirm it is current and that the assisted living community has a copy on file. Must
Locate the original Social Security card, Medicare card, birth certificate, and insurance policies and store them in one secure folder. Must

Financial review

Request a detailed, written fee schedule from the community covering base rent, tiered care costs, and any add-on charges before signing a residency agreement. Must
Have a licensed elder law attorney review the residency contract before signing, paying attention to discharge clauses and rate-increase policies. Must
Determine whether your parent may qualify for Medicaid assistance and, if so, contact your state Medicaid office or a benefits counselor to understand the timeline. Should
Confirm how long current assets can cover costs and build a written financial plan with a qualified financial adviser. Should

Care assessment and community selection

Request a written care assessment from the community that documents your parent's specific needs, including medication management, mobility assistance, and memory care if applicable. Must
Ask the community to explain how care levels are reassessed and what triggers a change in monthly cost. Must
Visit the community at different times of day, including a meal service, before finalizing a decision. Should
Ask for the most recent state inspection report, which assisted living communities are generally required to make available. Should

Logistics and household wind-down

Compile a list of every recurring charge tied to the current home, including utilities, internet, streaming services, and insurance, and set cancellation or transfer dates tied to the move. Must
Arrange for mail forwarding through the U.S. Postal Service and update the address with Social Security, Medicare, banks, and insurers. Must
Coordinate with family members on what personal items will move with your parent, keeping the room size and community policies in mind. Should
Arrange for the safe storage or distribution of remaining belongings and determine who will handle the lease termination or home sale. Should
Label your parent's clothing, glasses, hearing aids, and personal items clearly to reduce the chance of loss after move-in. Nice to have
Create a simple one-page contact sheet for the community listing family members, the primary physician, and the pharmacy. Nice to have

Sign nothing without professional review

Assisted living residency agreements are legally binding contracts that can be difficult to exit. Rate-increase clauses, arbitration requirements, and discharge conditions vary widely. Have a licensed elder law attorney review any contract before your parent or a family member signs it. This step protects both your parent's care continuity and the family's financial position.

Managing finances and household accounts after the move

Once a move date is confirmed, recurring household costs need immediate attention. Subscriptions, utilities, and insurance policies tied to the current home can continue billing long after the home is vacated if no one cancels or transfers them. A structured review of every recurring charge, similar to the approach described in auditing and simplifying household subscriptions, can prevent unnecessary spending during the transition.

Assisted living costs typically come from a combination of personal savings, Social Security income, pension payments, and, in some cases, Medicaid. Because Medicaid eligibility for assisted living is determined at the state level and involves asset and income limits, families should begin that review well before funds are depleted. For a broader overview of how Medicare, Medicaid, and other senior benefit programs interact, see Medicare, Medicaid, and senior benefits. General strategies for stretching fixed income during this period are covered in managing money on a fixed income.

Medicaid spend-down rules vary by state

Some states allow Medicaid to cover a portion of assisted living costs; others do not. Asset transfer rules and look-back periods also differ. Families who transfer assets without professional guidance may inadvertently create an eligibility penalty. Contact your state Medicaid office or a certified benefits counselor before making any financial moves intended to qualify a parent for assistance.

This article is for informational purposes only. It is not legal, financial, or medical advice. Consult a licensed elder law attorney, a qualified financial adviser, and your parent's healthcare provider before making decisions about assisted living or related financial and legal matters.

Senior Editorial Team

SmartGlobetrotter.net

Senior Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.

Senior
View author profile

The content provided on our blog site traverses numerous categories, offering readers valuable and practical information. Readers can use the editorial team’s research and data to gain more insights into their topics of interest. However, they are requested not to treat the articles as conclusive. The website team cannot be held responsible for differences in data or inaccuracies found across other platforms. Please also note that the site might also miss out on various schemes and offers available that the readers may find more beneficial than the ones we cover.